Best Workers’ Comp Insurance for Small Business
Best Workers’ Comp Insurance for Small Business
Last updated: March 2026
Small businesses pay a median of $54/month (about $643/year) for workers’ compensation insurance, though annual premiums range broadly from roughly $250 to $5,700 depending on industry, payroll, and location. Top-rated carriers for 2026 include ERGO NEXT (best overall, strongest for hands-on/physical industries), The Hartford (broad coverage, flexible bundling), biBERK (Berkshire Hathaway-backed, no broker markup), and Pie Insurance (algorithmic pricing, strong for restaurants and light construction). In most states, workers’ comp becomes legally required the moment you hire your first employee — it’s rarely optional once you have staff.
Workers’ compensation isn’t a nice-to-have once your business has employees — it’s typically a legal requirement, and going without it can expose you to direct financial liability for a workplace injury. Here’s what it actually covers, what it costs, and how the top carriers compare.
What Workers’ Compensation Actually Covers
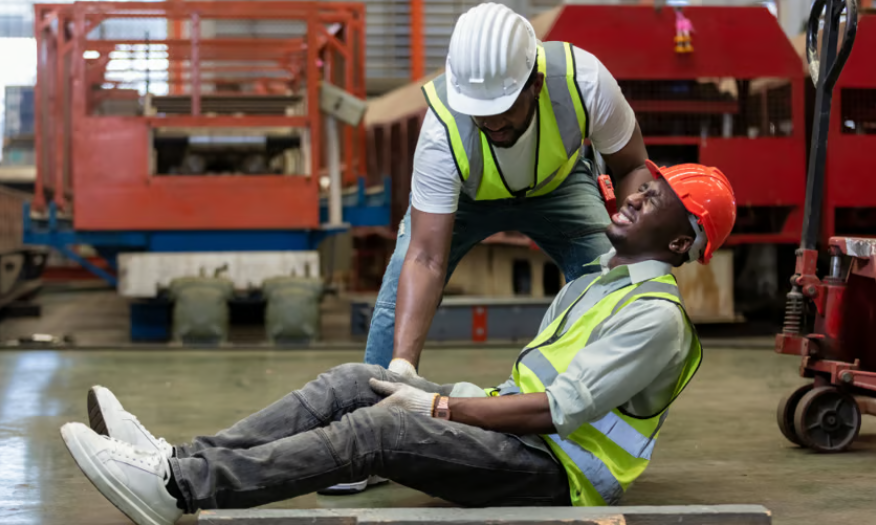
Workers’ comp provides medical, wage-replacement, and disability benefits to employees injured or made ill on the job — regardless of who was at fault. Most policies also include employer’s liability insurance, which covers legal defense costs if an injured employee sues your business directly, separate from the standard workers’ comp claim process.
Even self-employed individuals sometimes carry this coverage, since personal health insurance can deny claims tied to work-related injuries.
Do You Legally Need It?
In most states, workers’ compensation becomes mandatory the moment you hire your first employee — the exact threshold and rules vary by state, so it’s worth checking your specific state’s requirement directly rather than assuming. Even in states where it’s not strictly required for very small headcounts, most advisors recommend carrying it anyway: it protects your business from a potentially business-ending lawsuit if an employee is seriously injured and you’re uninsured.
Top Workers’ Comp Providers for Small Businesses in 2026
| Provider | Best for | Notable pricing |
|---|---|---|
| ERGO NEXT | Best overall; hands-on and physical industries | Averages ~$86/employee/month — about 24% below the national average |
| The Hartford | Broad coverage, flexible bundling, established brand | Most customers under $300K payroll average $81/month; some policies start as low as $13/month |
| biBERK | Berkshire Hathaway financial backing, no broker markup | Competitive direct-purchase pricing with pay-as-you-go billing |
| Pie Insurance | Restaurants, retail, light construction (algorithmic pricing) | Often lower premiums than generalist carriers for these specific industries |
| Progressive Advantage | Businesses wanting bundling with other commercial lines | Average ~$121/month; median lower at ~$76/month |
| Cerity | Very small businesses wanting simple, subscription-style billing | Starts as low as $25/month, cancel anytime |
| AmTrust Financial | High-risk industries other carriers decline | Covers class codes many online-first carriers won’t touch |
No single carrier is “best” for every business — the right fit depends heavily on your specific industry, business size, location, and whether you value the lowest price, broadest coverage, or a specialist who understands your exact trade.
What Actually Drives Your Premium
- Industry classification (class code) — the single largest factor; physical, high-injury-risk trades cost meaningfully more than office-based work
- Payroll — premiums are typically calculated per $100 or $1,000 of payroll, so total wages paid directly scales your premium
- State — workers’ comp is regulated at the state level, and rates for otherwise identical businesses can differ significantly by state
- Claims history (EMR) — your Experience Modification Rate reflects three to five years of claims data; a single serious past claim can keep your rate elevated well beyond that incident
- Business size — smaller headcounts generally see lower absolute premiums, though the rate per employee doesn’t necessarily drop as you grow
Pay-As-You-Go vs. Traditional Annual Premiums
Several newer carriers (Cerity, biBERK, and others) now offer pay-as-you-go billing — you pay monthly based on actual payroll rather than a large upfront annual premium based on an estimate. This has two real advantages for small businesses:
- Better cash flow — no large lump-sum payment due at policy start
- More accurate billing — since payroll fluctuates (seasonal hiring, part-time staff), pay-as-you-go avoids the large “true-up” bill some traditional annual policies charge at renewal if your actual payroll ended up higher than estimated
Traditional annual premiums can still make sense if you have very stable payroll and prefer one predictable payment rather than variable monthly billing.
How to Lower Your Workers’ Comp Premium
- Compare quotes from at least 3 carriers — pricing for an identical business profile can vary substantially between insurers, since each applies its own underwriting adjustments
- Invest in workplace safety — since your EMR reflects multiple years of claims data, reducing incidents now protects your rate well beyond the current policy term
- Classify employees correctly — misclassifying a lower-risk role under a higher-risk class code (or vice versa) can meaningfully affect your premium; review your class codes at renewal
- Consider pay-as-you-go billing if your payroll fluctuates seasonally, to avoid overpaying on an estimated annual premium
- Ask about bundling — some carriers, including The Hartford, offer pricing advantages when workers’ comp is bundled with general liability or a Business Owner’s Policy
General Insurance Cost Calculator
Frequently Asked Questions
How much does workers’ compensation insurance cost for a small business? The median cost is about $54/month (roughly $643/year), though annual premiums range broadly from about $250 to $5,700 depending on industry, payroll, location, and claims history.
Am I legally required to carry workers’ comp insurance? In most states, yes, once you hire your first employee — though the exact threshold and rules vary by state. Even where not strictly required, most advisors recommend it as protection against a potentially business-ending lawsuit.
Which company has the best workers’ comp insurance for small businesses? There’s no single best provider for every business. ERGO NEXT, The Hartford, biBERK, Pie Insurance, and Cerity each lead in different categories — pricing, financial strength, industry specialization, or billing flexibility — so the right fit depends on your specific business profile.
What’s the difference between pay-as-you-go and traditional workers’ comp billing? Pay-as-you-go billing charges you monthly based on actual payroll, improving cash flow and avoiding a large “true-up” bill if your estimated annual payroll was too low. Traditional annual premiums require a larger upfront payment based on an estimate.
Does my personal health insurance cover work injuries instead? Not reliably. Personal health insurance can deny claims tied to work-related injuries, which is one reason even self-employed individuals sometimes carry workers’ comp coverage.
How can I lower my workers’ comp premium? Compare quotes from multiple carriers, invest in workplace safety to protect your EMR over time, ensure employees are classified under the correct class code, and ask about bundling with other commercial coverage.
This guide reflects publicly available carrier and industry pricing data as of September 2026. Workers’ compensation requirements and premiums vary significantly by state, industry, and carrier — always confirm current requirements with your state’s labor department and request a formal quote from a licensed agent before purchasing.

1 comment