Professional Liability Insurance Cost by Industry
Professional Liability Insurance Cost by Industry
Last updated: September 2026
Professional liability insurance (also called errors and omissions, or E&O) averages roughly $56–$88/month nationally for a small business with $1 million in coverage, but the real number depends almost entirely on your industry. Cleaning services pay as little as $19/month — about 67% below average — while childcare services pay as much as $166/month, roughly 195% above average, for comparable coverage. Mortgage brokers and accountants also run well above the median, often 85–115% higher, since a professional mistake in those fields can trigger six-figure claims.
If general liability covers someone tripping in your office, professional liability covers something very different: a client claiming your advice, work, or a missed deadline cost them money. For service-based businesses, it’s often the single most important policy in the entire insurance program — and the cost varies more by industry than almost any other coverage type.
Best Business Owner’s Policy (BOP) Providers
Professional Liability vs. E&O vs. Malpractice: Same Coverage, Different Names
This trips up more business owners than it should — these are largely the same coverage, just labeled differently by industry convention:
- Professional liability — the term most common in construction, engineering, and consulting
- Errors and omissions (E&O) — the term most common in technology, real estate, and financial services
- Malpractice insurance — the term used in medical and some legal fields
The underlying mechanics — claims-made policy structure, exclusions, and what triggers a payout — are functionally equivalent across all three names. What matters is confirming the coverage details, not the label on the policy.
What It Actually Covers (and Doesn’t)
Professional liability covers claims tied to your professional services specifically — not physical accidents at your worksite, which is what general liability handles instead. Covered claims typically include:
- Negligence or mistakes in the advice or service you provided
- Missed deadlines that caused a client financial harm
- Inaccurate advice or a failure to deliver services as promised
- Legal defense costs, even if the claim against you is ultimately unfounded
What it explicitly does not cover: intentional wrongdoing. If you deliberately defraud a client, steal funds, or purposefully cause financial harm, professional liability insurance will not defend or pay out on that claim — it’s strictly for negligence, mistakes, and oversights.
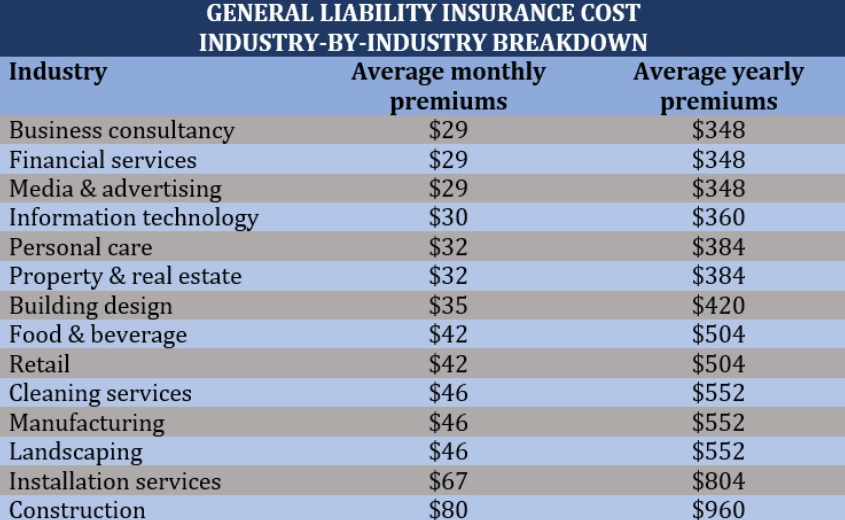
Cost by Industry: The Real Spread
| Industry | Typical cost vs. national average | Notes |
|---|---|---|
| Cleaning services | ~67% below average (~$19/mo) | Lowest-cost category; risk profile leans toward bodily injury/completed operations, better covered under GL |
| Consulting, tech, general services | Often below the $56–$88/mo average | Lower claim severity than regulated financial/childcare fields |
| IT consultants & MSPs | $1,000–$3,000/year | System failures, data loss, and project delays are the most common claims |
| Accountants & CPAs | $800–$2,500/year (85% above average) | Errors can directly cause significant client financial loss |
| Mortgage brokers | 115% above average | Mistakes frequently trigger high-dollar disputes |
| Childcare services | ~195% above average (~$166/mo) | Highest-cost industry by a wide margin — most claims involve alleged negligence toward children |
Two other factors matter almost as much as industry: employee count (premiums scale from solo practitioners up through 20–49 employee bands) and location — professional liability costs in New York or California run around $1,100/year on average, roughly $400 more than lower-cost states like North Carolina or North Dakota.
What a Typical Small Business Actually Pays
Pulling together figures from several 2026 industry sources:
- National average: roughly $56–$88/month ($675–$1,051/year) for a small business (1–4 employees) with $1 million per claim / $1–2 million aggregate limits
- Annual range: most small businesses pay $400 to $3,000/year, with 43% of one major broker’s customers paying under $75/month
- Higher-risk industries: can run $3,000 to $12,000+/year, depending on claim severity and frequency in that field
Treat any single “average” cautiously — the spread across data sources exists because sample sizes, business profiles, and coverage limits differ between studies.
Understanding Tail Coverage
If you cancel or don’t renew a claims-made professional liability policy, you generally lose protection for claims arising from work performed before the policy ended, once the policy itself lapses. Tail coverage (also called an extended reporting period) extends your ability to report those claims after the policy ends — typically costing 100–200% of your annual premium as a one-time purchase. This matters most if you’re closing a business, changing insurers, or retiring from a professional practice — don’t let coverage lapse without considering whether you need it.
How to Lower Your Professional Liability Premium
- Raise your deductible — moving from a $1,000 to $5,000 deductible can meaningfully cut your monthly premium
- Compare quotes across multiple carriers — pricing for an identical business profile varies significantly by insurer
- Review your coverage limits against actual contract requirements — carrying more than any client or contract requires is a common way businesses overpay
- Maintain a clean claims history — since claims-made pricing is sensitive to your track record, avoiding preventable disputes protects your rate over time
- Bundle where possible — some carriers offer pricing advantages when professional liability is combined with general liability or a BOP
Frequently Asked Questions
How much does professional liability insurance cost per month? Nationally, roughly $56–$88/month for a small business with $1 million in coverage, though the real cost depends heavily on your industry — from as low as $19/month for cleaning services to $166/month for childcare services.
Is professional liability insurance the same as errors and omissions (E&O) insurance? Yes, essentially. They’re the same coverage under different industry naming conventions — professional liability is more common in construction, engineering, and consulting, while E&O is more common in tech, real estate, and financial services.
What’s the difference between professional liability and general liability insurance? General liability covers physical injuries and property damage at your worksite. Professional liability covers financial harm caused by your professional services — negligence, mistakes, missed deadlines, or inaccurate advice.
Why is childcare the most expensive industry for professional liability insurance? Because the vast majority of claims in that field involve alleged negligence regarding a client’s children, which insurers price as a high-severity risk category — running roughly 195% above the national average.
What is tail coverage and do I need it? Tail coverage extends your ability to report claims from work performed before your claims-made policy ended, after the policy itself lapses. It typically costs 100–200% of your annual premium as a one-time purchase, and matters most if you’re closing a business, switching insurers, or retiring.
Does professional liability insurance cover intentional wrongdoing? No. It covers negligence, mistakes, and oversights only — intentional fraud, theft, or deliberately causing financial harm is explicitly excluded from coverage.
This guide reflects publicly available insurer and industry pricing data as of September 2026. Professional liability premiums vary significantly by industry, state, employee count, coverage limits, and claims history — always request a formal quote from a licensed commercial insurance agent for your specific business before purchasing.

1 comment